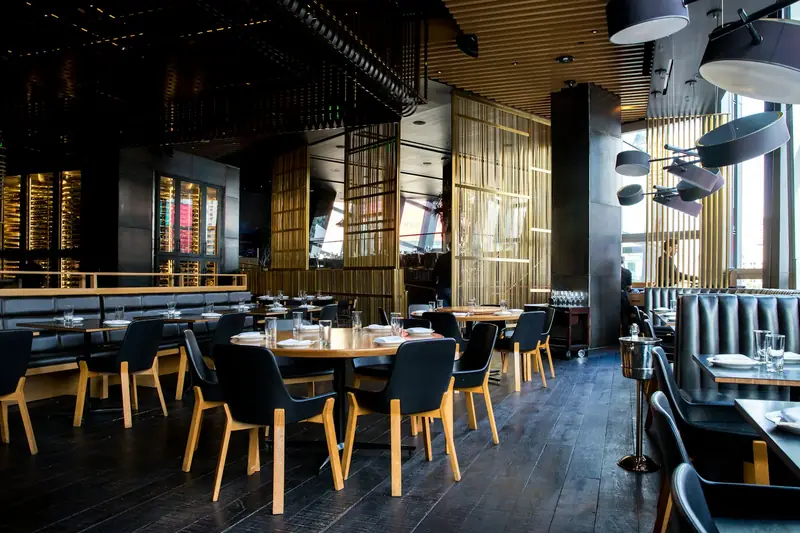
Restaurant loans in Memphis often start with a question most cities never ask: how much smoker can the building handle? Barbecue is part of the city’s identity, and pits, wood storage and ventilation shape budgets from Downtown to East Memphis. This page focuses on financing Memphis restaurants specifically, from Cooper-Young and Overton Square in Midtown to South Main and the suburbs. The Memphis city page covers the wider economy, from FedEx to festival season.
What Memphis restaurant owners finance
- Smokers, pits and ventilation. Commercial smokers and the hood, fire-suppression and exhaust work around them are often the most expensive line items in a barbecue kitchen. Restaurant equipment financing can cover freestanding equipment, while built-in pits are usually treated as renovation work.
- Build-outs in older buildings. Many Midtown and Downtown restaurants occupy early twentieth-century storefronts that need new plumbing, grease interceptors and electrical upgrades before a kitchen can open.
- Buying the building. Property in many Memphis neighborhoods is more attainable than in Nashville, so owner-occupied real estate is a realistic goal for established operators.
- Acquisitions. Buying an established restaurant with a loyal following and a lease in place.
- Catering capacity. Many Memphis restaurants also cater, which can justify extra equipment, vehicles or a commissary kitchen. See catering business financing.
Loan types that fit
- SBA loans, including 7(a) for acquisitions and working capital and 504 for real estate and major equipment.
- Commercial real estate loans for buying or refinancing your building.
- Construction and renovation loans for build-outs and code upgrades.
- Equipment financing for smokers, ranges, coolers and POS systems.
- Working capital loans to prepare for the Memphis in May season and carry slower summer weeks.
- Expansion loans for owners heading to Germantown, Collierville or Bartlett.
Permits and approvals in Memphis and Shelby County
Shelby County is one of the Tennessee counties where the local health department, not the state, handles food service permits and inspections, so plan review goes through the Shelby County Health Department. Building permits run through the joint Memphis and Shelby County code enforcement office. Beer permits inside city limits come from the Memphis Alcohol Commission, and liquor-by-the-drink licenses come from the Tennessee Alcoholic Beverage Commission. For SBA questions, Shelby County businesses can call the SBA’s Memphis virtual office, and in-person appointments happen at the Tennessee District Office in Nashville. Free consulting is available closer to home at the Tennessee Small Business Development Center’s Memphis office on East Shelby Drive.
Preparing a strong Memphis application
The starting point is our short application and your three most recent months of business bank statements. Add equipment quotes for smokers or kitchen packages, contractor bids for any build-out and the lease or purchase contract. Owners buying a restaurant should gather the seller’s financial statements and tax returns. If your concept includes a full bar or late-night program, also read bar financing in Memphis.
Questions owners ask
How do I finance a restaurant in Memphis?
Most Memphis restaurant projects combine financing types. Equipment loans often cover smokers and kitchen gear, renovation or SBA loans cover the build-out, and working capital covers opening payroll and inventory. Established owners may also finance the building itself. A broker sends one application to several lenders so you can compare structures and terms.
What does a Memphis restaurant build-out need permitted?
Expect plan review and a food service permit from the Shelby County Health Department, building permits through the joint Memphis and Shelby County code enforcement office and fire approvals for hoods and suppression systems. Serving alcohol adds a Memphis Alcohol Commission beer permit and a Tennessee Alcoholic Beverage Commission license. Lenders often schedule draws around these steps.
Can I get an SBA loan for a Memphis restaurant?
Yes. Restaurants are eligible for SBA 7(a) loans, often used for acquisitions and working capital, and SBA 504 loans for real estate and major equipment. Approved banks and lenders make the loans. Shelby County owners can call the SBA’s Memphis virtual office with program questions, while a broker helps find lenders actively financing local restaurants.
What do lenders want from Memphis restaurant owners?
Lenders review time in business, recent bank deposits, existing loans or advances and personal credit. For build-outs and new locations they also look at the lease, contractor bids and your cash contribution. Seasonal patterns around Memphis in May and summer heat are normal, but explaining them up front helps lenders read your statements correctly.
Related pages
Explore the Memphis city page or browse all cities on the Tennessee hub. Ready? Check what you qualify for.